Friday, May 24, 2013

April - May Expenses


The months keep rolling on and the temperature keeps rising.  I really enjoy this time of year in Japan.  It’s right before the rainy season hits in which, next to winter, is my least favorite time.  But for a brief period it’s warm enough to bike in just shorts and a t-shirt, stay out enjoying the company of friends till all hours, and basically hit the out doors any time.  Picnics and days at the beach (as well as the end of the first term of school and summer break) are just over the hill.

Of course I still have a job which means I only really get to enjoy about 7 or 8 days max of this fine fine weather.  The other days are spent in a suit and tie in a classroom.  I don’t mind teaching, it’s a challenging, and very rewarding field.  Sure I get upset at students, and not every less plan I make is a winner.  But, it sure beats the nine to five in other fields. 

Alas teaching is still mandatory.  I must teach in order to live.  I’m aiming to one day have everything in my life be about choices.  One day I can choose to get up and go teach while the next day maybe enjoy one of those picnics or days at the beach.  In order to achieve this level of freedom I have to be careful with my money and that is why I track my expenses every month, down to my very last yen.  I do this myself in an excel workbook of my own design.  Let’s see how I did:


INCOME

Paycheck:  ¥299,484

Gympact:  ¥1,000

TOTAL:  ¥300,484

Income fell this month.  I didn’t do any work at my part time job during the March to April pay period.  I was on vacation and also preparing for the new school year that began in April.  It’s too bad that I couldn’t get any extra work in but at the same time I didn’t want to push myself beyond what I know I can handle.  In addition my job forgot to add my raise onto my paycheck (it was added to the next paycheck) and the transportation expense I thought I was going to receive is now being split up monthly so I’ll be seeing that next month.


EXPENSES

Rent:  ¥50,100

Eating Out:  ¥28,963

Groceries:  ¥15,784

Transportation:  ¥3,730

Bills:  ¥7,905

Entertainment:  ¥300

Alcohol:  ¥3,993

Bike:  ¥14,847

Travel:  ¥30,440

School Supplies:  ¥520

Fees:  ¥1,944

TOTAL:  ¥158,526

SAVINGS RATE:  47.34%

Expenses were certainly higher this month.  I paid off my credit card which included my bullet train ticket to Hiroshima in March for the bike trip I took with my GF.  It also included some bike tools like a large torque wrench, some players, and bits.  I’m happy to report there has been little to no activity on the CC lately so the coming months will be quite nice.

My savings rate for this month was 47.34% and here are the savings rates for the year.

March  42.85%

February  65.43%

January  47.36%

My average savings rate for the year is 51.88%.  This is below my target goal of 55%.  Due to the setback in receiving my raise and the extra expenses this month I once against missed my target goal.  The high savings rate for February is helping to keep my average up.  I’ve been busy at work so I haven’t been going out lately which means I see higher rates going forward for the rest of the year.  August in particular will be a good month as I get six weeks paid vacation during which time I can still work at other jobs. 
How's everybody else doing?

Friday, April 26, 2013

March – April Expenses and 1st Quarter Dividends


Things have been quite hectic lately with my school moving locations, a new route to bike, new students and lesson plans, etc.  It doesn’t mean I’ve forgotten about investing however or living a frugal life.  I can always do better at both but just giving it a shot puts me on the front lines of a happy fulfilling life where my time is my own.

I track my expenses from the 15th of one month to the 14th of the next.  Here is what happened from March to April (Numbers are in Japanese Yen):

Income:

Paycheck:  299,904

Part-time Job:  18,394

Questionnaire:  500

Selling stuff:  1,240

TOTAL:  320,038

My income was pretty much where I thought it would be.  Down quite a bit from February but that’s only because February had quite a spike in it with the STEP Eiken test and discovering 50 hours of unused vacation time from my part-time job.  Next month I will receive a raise at work (which was forgotten on my April check so I’ll get double the raise in May) and also start receiving travel expenses monthly.

Expenses:

Rent:  50,100

Eating Out:  45,364

Groceries:  10,578

Transportation:  4,950

Bills:  6,696

Entertainment:  1,200

Alcohol:  4,817

Bike:  18,666

Medical:  550

Present:  25,701

Videogames:  1,515

Lodging:  12,770

TOTAL:  182,907

SAVINGS RATE:  42.85%

AVERAGE SAVINGS RATE 2013:  51.88%

Expenses came in a bit harsh this month with some winners and a few losers.  I bought my GF a nice present for Valentine’s Day in February which means I had to pay the CC in March.  A few drinking parties with the new teachers at my school plus the spring break bug to get out and catch some brews with friends had me forking over more cash for “catheter and tube” drinks.  Bills and Medical were wayyyy down and have been down compared to last year.  I canceled my postpaid phone and went prepaid in January and I’ve been taking much better care of my teeth so my dental visits are just for checkups and maybe an x-ray. 

My yearly goal for the year is to save 55% of my income.  So far my average is 51.88%.  I’m not very worried about this going forward as I mentioned I’m receiving a raise at work and I’ll start to collect transportation expense for the train even though I am taking my bike.  In addition I don’t have any big plans for the summer so I will try to get some time in at my part time job while still collecting a paycheck from my employer (I get paid summer, winter, and spring breaks).  In addition there are still two more STEP Eiken tests this year which will help to pad my bottom line.

1st Quarter Dividends

As I buy more stocks I get paid more dividends.  It’s that simple really.  My first quarter of 2013 saw a blowout compared to last year.

Total Dividends Received 1st Quarter 2013:  $178.96

Total Dividends Received 1st Quarter 2012:  $44.17

Wow!  A more than 300% increase over last year!  I’m pretty happy with that!  Of course the best part is that all of these dividends are being reinvested so they will pay me more the next time around.  And if the company decides to increase the dividend, well, it just doesn’t get any better. 

Friday, April 12, 2013

Double Whammy

As anybody investing in stocks knows the market is pretty expensive right now.  Almost anything that I bought a year ago is up ten to twenty percent!  The market has recovered all of its value that it lost in the crash of 2008 and I'm not sure if it is showing any signs of slowing down.  Of course this makes things like the value of my portfolio look nice but in reality it's not the game that I want to be playing.  Not that it's impossible, but it is certainly more difficult to find value in this market.

Another problem that effects us expats is the exchange rate.  As any expate living abroad and sending money home is aware the exchange rate is like an extra hoop you have to bring into the equation.  For expats it's having to line up two scopes before we can pull the trigger on a deal. 

In the last two or three years living in Japan has been great!  The Japanese yen grew to new heights that had never been seen.  Of course this was not good for Japanese businesses as their products were now more expensive and exports fell.  But for us expats using yen to buy US dollars it was a breath of fresh air.  I never thought I'd ever see the day when 75 yen would buy me 1 US dollar.  Those were the days I lived in for the last three or so years.  It was like everything was 25% off including stocks, plane tickets, and gadgets.

This is not the story as of late.  Due to a change in the Japanese government, renewed consumer confidence, and an aggressive stimulus plan the yen has taveled back to being on par with the US dollar.  This means a big change for me and my salary. 

I did my best to abstain from squandering my money on frivilous items and focused on putting everything I could into stocks even during the days of a strong yen.  But I also developed an expectation of how much I could buy with my yen.  For an example let's say I was making $60,000 US dollars last year.  I did my best to save and invest and mangaged to achieve an almost %50 savings rate.  Now my salary has fallen to almost $45,000 a year.  If I continue at the same spending rate as last year my savings rate will fall to almost 33%.  Of course this isn't a complete apples to apples comparison but the point is my yen will no longer buy me the huge number of shares that it used to.

This has led me to a cross roads where I have to make a few important decisions.  Do I pick up another job and try to earn more?  Do I continue to invest in US dividend growth stocks?  Do I change my focus to the Japan domestic  market?  Where can I reduce expenses more?

Honestly I haven't made a decision yet concerning any of these.  Any other expats out there what's your take on the situation? 

Wednesday, March 27, 2013

February - March Expenses

Well here we are at almost one quarter of the year gone by!  I recently posted about a milestone I hit but that doesn't mean I'm stopping.  No surrey bob!  That is just one little step on my way to a life of choices.  In fact to be honest I should celebrate $30,000 as much as I should celebrate $30,001.  I can't make every blog post about the value of my portfolio, however, but it's still fun every now and then.

What really matters in my journey to FI are these posts right here.  My expense posts outline my spending every month.  It shows my offensive and defensive strategies and just how well they are working.  Offensive is my income.  Am I making the best use of my time or am I just slagging off on the weekends.  Defensive is my spending.  How well am I controlling my urges to buy the latest widget or gadget?  How often to I really need go out to eat with my buddies?  Let's take a look:

Income:
Paycheck:  ¥299,404
Part Time Job:  ¥102,755
Part Time Job 2:  ¥27,000
Questionnaire:  ¥5000
Total:  ¥434,159

My income was pretty insane this month.  I received my regular pay in addition I discovered some unused vacation time at my part time job and asked to receive the whole lump sum ASAP (got to get that interest working in my favor).  The Step EIKEN test was also held where I am an interviewer (part time job 2).  In addition a friend introduced me to a survey where for answering almost 400 questions in Japanese and 400 questions in English I can earn ¥5,000.  Not bad, but I have to admit it was a drag getting through it all in one sitting.  Over all this might have been my best month ever as far as income goes.

Expenses:
 Total:  ¥148,334

Expenses weren't out of line with where they usually are.  I suppose because of "Presents" it was a bit high.  This year I sent out my X-mas album late and so, I paid off my credit card in the month of February.  I track my bills by when I actually pay them so this expense landed in the second month of the year.  This should be the last month that "BIlls" will be as high as it is.  I'm completely clear of my old cellphone bill now, and riding high on prepaid.

My target savings rate for the year is 55%.  So far I've hit:

January - February:  47.36%
February - March:  65.43%

My average savings rate for the year is 56.40%.  Not bad!  It looks like we are back on track.  I'll admit that March - April is already shaping up to be a bit of a struggle with end of year school parties, a bike trip, and possibly a fun weekend at Fujikyu Highlands.  I'm all about enjoying my money while I have it as well, but I am sure not gong to forget about my goals. 

Thursday, March 7, 2013

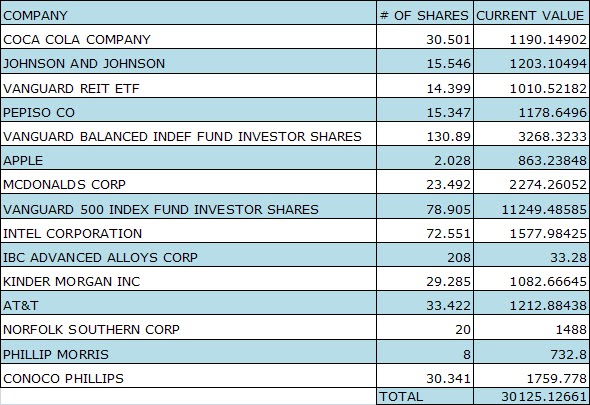
Milestone: Portfolio Surpasses $30,000!

I've been in Japan for the last little while but that doesn't mean I haven't been watching the market.  If you haven't been following, the market is on fire like the flames from Mt. Doom (in Mordor).  Because of that it's pushed my portfolio passed the $30,000 mark!  This is a big achievement for me.  I have never had this much money at my finger tips before.

I could, if I so wanted, go out and buy a Mini Cooper right now with zero need to go to a bank.  I could, if I was so persuaded, take a huge long vacation staying in expensive hotels and dining at the finest restaurants.  I could even, if the feeling so arose, pay for a six year college education including one year of study abroad in Japan (I should know).

However I don't feel like doing any of those things.  In fact the next vehicle purchase I make will probably be more than ten years down the road and it will be a bike.  My next vacation is being taken on a bike.  And, although I don't think I'm going back to school anytime soon (not that I didn't have a good time), my next educational foray will probably be via Treehouse.

Perhaps the surreal thing is that although it took me about four years to pay off six years of college, credit cards, and a car, it's only taken me fourteen months to save up a stash equating to 85% of that same amount.  That really demonstrates: how interest rates kill you if you aren't on the receiving end of them, and the job of money is to make money.

Back in January I revealed for the first time what I am holding.  At that time my portfolio was worth $25188.70.  With the recent drive in value by the market I just hit $30125.13!  That's an increase of almost $5000 in about two months.  Not to keeping adding cherries on top but I still have capital that I want to deploy.


I'm not a genius.  Looking at my portfolio people might be confused.  "Apple!?  That's not a dividend paying stock!"  "Why's he buying individual equities but also Vanguard 500?"  Well that's because I'm not a genius.  And yet here I am on my way to FI.  I am also not a big enough fool to think this can't go back down.  In addition it's more about how much the portfolio firing off in dividends than it's actual total value.  But I'm not going to ignore the obvious correlation between portfolio size and dividend payout.  Put simply "the more, the more."

Frankly a stock sell off would be pretty cool right now as it's getting harder to find good values.  But in the mean time I'll enjoy the view from 30,000.

Mata ne,

Kechi

Monday, February 25, 2013

January - February Expenses

The first month of my fiscal year has gone by.  I've made some changes lately that I hope to see bring my expenses down but I might not see the effects of them for a few months down the line.  My recent change to a prepaid plan is one example.  I should also be receiving a raise at work soon as well as the first part of my transportation expense in April.  This should go a long way in helping me hit my yearly goal of stashing 55% of my salary in 2013.

For January to February I had:

Income:
Paycheck: ¥299,904
Part Time Job: ¥16,619
Xmas Money: ¥8,970
Gympact: ¥1,794
Total:  ¥327,287

A respectable month I suppose. For some reason my taxes went up about ¥500 so it's pushed my main pay check under ¥300,000. My forthcoming raise should push my back up over however. I did some moderate work at my weekend job, received some late Christmas money and got paid twice from Gympact.

Expenses:

Total:  ¥173,275

Doing the math that leaves ¥155,012 left over that I invested.  That's a 47.36% savings rate.  Hmmm...  Well, that is below 55% but it's still pretty respectable.  As always dining out restaurants was expensive.  In this case it had to do with "entertainment" as well.  As I outlined before "entertainment" expenses and "eating out" expenses tend to go hand in hand.  In this case we went out with a spend-aholic friend of mine (doesn't make him a bad guy!) to watch sumo.  It was great but I paid for the ticket for both me and my GF and also for lunch and some of dinner.  That right there was probably 10% of my spending for the whole month!  And, just imagine this buddy of mine lives like this all the time!  

Bills were still quite high as I paid off my last month of Softbank postpaid service.  I also had to visit a clinic as I was having some pains in my wrist last month.  

A quick note as well.  Starting next month I will no longer be counting the "House" as an expense.  This will start going under my investments.  I think it's starting to get closer to being a real vacation house that can be rented out and that the money I'm putting into is not just getting thrown down the toilet like on a cellphone.

Thursday, February 14, 2013

Going Prepaid


A number of months ago MMM described how he lowered his cellphone bill by almost 90% by going prepaid and using an MVNO service.  He was able to unlock his iPhone and keep it's functions while paying a fraction of the price.


I, like most people, have had a cell phone for a number of years and just accepted that it's ¥8,000 (about $90) a month for the privilege.  I shopped around as much as I could for a cheaper plan but for a smartphone ¥8,000 is about as good as it gets.  In fact if you want one of the newer models, like the iPhone 5 with LTE service, it's going to cost you even more money.

Since waking up and doing my best to crawl out of the consumer sand trap I knew there had to be a better cheaper way to get cell service even in a country like Japan.  Low and behold there was and is.  Prepaid.

You're getting what!?!

People seem to gawk when you mention prepaid service.  It has an air of being unrefined or less prestigious than post paid service.  I don't know if it's the more expensive rates (which is true, prepaid is in general more expensive on a minute per minute basis), the idea that people on prepaid must not use their phone much and therefor not be social and popular person, or that prepaid phones tend to be bare bones and boring.  

Well I never used my smart phone much for calling so the rates didn't really matter to me.  I stopped caring quite a while ago about my phone as a status symbol and, finally, I started to question just how useful smartphones really are.

Let's talk about what I had.  I bought an iPhone 4 two years ago with Softbank.  I paid ¥4,200 a month just for data.  It was unlimited but I couldn't tether to a computer and while the speed was decent I found I was usually at home or at work where I have wifi.  My calling plan cost ¥980 a month for the "White Plan."  On Softbank you don't receive a bucket of minutes instead you pay a price for certain rate.  On the "White Plan" I received unlimited calling to other Softbank customers from 1am to 9pm every day and after 9pm or if I called outside of the Softbank network it was ¥21 for 30 seconds (basically about $0.50 a minute).  In addition there was a "discount features set" for about ¥500 (voice mail, call waiting, caller ID, etc...) and then the cost of the phone itself was broken up over the life of the contract (Japanese carriers don't subsidize the cost of the phone directly).

Sounds pretty standard but I'm not looking for standard.  I barely called anybody except maybe my GF, and I really wasn't using the data plan.  Other than emailing, and texting, I used my phone to check Facebook quite often or maybe mess around with a random app.  However, other than apps to track stocks there wasn't a useful function for the smartphone.

Not mine but similar

So I decided to drop the whole box of rocks when my contract came up for renewal and get prepaid service.  For ¥8,000 (what my plan was costing me per month) I got a brand new "dumb phone" and a prepaid calling card.  What does my plan look like now?  Well I'll tell you there really is no comparison.  Softbank prepaid looks like this:

-Register a ¥3,000 yen card for 60 days.  If you don't register a new card 60 days from that card your minutes expire.  If you register a new card everything rolls over for another 60 days.  So basically I pay ¥1,500 a month.

-Calling rates are ¥90 a minute (about a dollar per minute, but remember I use about five minutes a month to call out).

-¥300 yen a month (which comes out of the ¥3000 prepaid card) for UNLIMITED email and texting.  I can text or email both Softbank subscribers and people on other networks.

-Incoming calls are completely free.  If I receive a call I can talk for an hour or ten and there is no charge to me.  And if the other person is a Softbank subscriber it's free for them to call me!

-Even if my minutes expire and I don't register a new card I can still receive incoming calls and I keep the same phone number and email for a year.  So if I go home for two months and don't want to pay I just let my time expire and start up again when I come back.

-The dumb phone is actually pretty smart.  It has a nice color screen, plays music, videos, and even has a built in TV tuner!  I can take movies and photos with it and still email them out.  Frankly it does just about everything I was doing on my iPhone.

-Perhaps the best feature is I have choices now.  If it doesn't work out I can always go get another contract.

Also, I still use my iPhone 4.  Even without network service the GPS works like a champ for tracking my bike rides in Runkeeper and sending that data to Gympact which net's me about $10 a month.  The iPhone still works on wifi so it's great for checking my email or stocks while I'm at my desk (which was where I checked that stuff anyway).  When I do find myself out and about without data I noticed that I don't miss Facebook or looking up random news articles on Lifehacker.  Now I read, study Japanese, or listen to music.  In addition there are still ways to interact with Facebook via email to post status updates and pictures.  Plus most if not all my friends still have smart phones on regular plans.  If for some reason I just have to know who was in "The Devil's Advocate" (Keanu Reeves, Al Pacino and Charlize Theron, released in 1997) I can ask a buddy.

Looking at the long run this move will save me almost ¥80,000 ($900) a year or more in cell phone related charges.  The only downside is I have to carry both the cell phone and my iPhone with me but I'm still looking into getting my iPhone 4 unlocked and using it as the prepaid phone.  Unfortunately Softbank does not supply unlock codes to it's customers even after they are off contract.  :(


It's been about one month since I made the switch and I'm very happy.  It's actually nice to have a phone that is just a phone again.  It's not complicated and the money I'm saving and investing could buy me cell phone service for life!  Now, that to me sounds like a plan.