Tuesday, June 25, 2013

Is it really so easy?

I'll be honest, I've gotten used to getting emails from optionsxpress.com now.  I get updates about thing like webinars, newsletters, etc.  Of course I also get emails about pending dividends.  All of these things have become just another email in my inbox.

When I first started investing back in January of 2012 I remember getting one of my first emails saying that I would receive an $8.00ish dividend from Pepsi Co. I believe.  A light went off in my head and I remember thinking "It can't be this easy."  Okay sure, $8.00 isn't a whole lot of money really.  A few beers or a meal at a fast food restaurant.  But it was free.  Or at least it felt like free.  Someone was just "giving" me $8.00.  It felt too easy.

Of course I was getting that $8.00 because I had given the company almost two hundreds times that amount.  But the crazy thing was was that I didn't have any plans for that money anyway.  I normally had been spending that money on student loan payments so it wasn't as if my life felt affected in any way.  Except that now I was investing instead of paying off my debts.  I'll also add that my life has been pretty sweet.  Even while paying down my debts aggressively I traveled, ate and drank out, visited home, and bought gadgets.  Maybe I've reigned in some of that spending a bit, but that reduced spending has in no way affected my happiness.  In fact the reduced spending, increased investing, and perpetually raising dividends have put me into a state of euphoria.  Well that and the bike riding.  

Like I said I'm used to getting the emails now.  "Pending cash dividend..." it usually says.  Then the amount and a date and a "amounts might not show up right away" blah blah blah.  What I'm still not used to is the feeling of how easy this all seems.  

How is this not the norm!?  Doesn't everybody want freedom?

After all sites that taught me how/why to get on this road get more hits in an hour than I have since the inception of this blog (just passed 10,000 after a year and a half!  Wahoo!)  I'm no rocket scientist.  In fact to share a little secret with you I've never even looked at a balance sheet since a marketing class in college.  And yet here I am, on my way.  How/Why/WTF are people not figuring this out?

I know I am on my way because I've done the math and I see where it goes.  I was skeptical at first.  Especially when I went into the red for a spill.  But the longer I've been on this path the more I am convinced I'm on my way to a place called Choice.  It will be bumpy.  But I am going there nonetheless.  


Saturday, June 15, 2013

Death Of Teacher.


Don't let me scare you with the blog title there.  I'm not dead nor am I dying in the traditional sense.

I've been feeling very depressed lately and haven't felt the energy to keep regular updates on the blog.  Don't worry I didn't fall out of my frugal habits, as the monthly expense updates have shown, but things at work have taken a turn for the worse and the money isn't feeling "worth it" anymore.

Well I suppose to get specific my job is now half a dream and half a nightmare.  Unfortunately the nightmare half keeps me up at night, stresses me out, and is changing me.  Even my GF points out that "I never used to say things like that," "Never used to talk like that about work," etc.

Normally I'd just throw in the towel and call it a day.  I'm a guy with experience and think my skills are valuable.  I'm pretty sure It wouldn't be all that difficult to find some part time gigs that pay me up to what I am making now while having more flexible hours, or just getting a new job.  I also have a good work ethic.  Which in this case means I want to stay loyal to the "dream" part of my job.  There are quite a few students who are counting on me to be there for them.  This is what is keeping me there now.

However that means having to put up with the "nightmare" half which I really really really don't want to do.  But my contract runs until next March.  All it seems I can do is count the days ever so slowly.

I'm trying to expand my options using TreeHouse to learn how to program iOS applications.  I'm pretty impressed so far with the trial lessons they make available on their website.  At only $25 a month it seems like a frugal/smart way to improve my skills and possibly move into a new career.

It's three more weeks until summer vacation which means I'll get about two months to relax.  I already know that it won't be easy as I'm just going to be counting the days until term two starts and that will keep me up at night.  I'd like to be very productive during these two months however and focus on TreeHouse as well as working part time to earn some extra cash.

A blog I like to read often is called Rob Evolves.  On there he posted a link to a Saturday Morning Breakfast Cereal comic that really opened my eyes.  I'll reproduce the text of the comic here but please check out his blog and SMBC as well.

"Here is something true:  One day you will be dead.
Here is something false:  You only live once.
It takes about seven years to master something.
If you live to be 88 after age 11, that is, you have 11 opportunities to be great at something.
These are your lifetimes.
Most people never let themselves die.
Some are afraid of death.
Some think they are already ghosts.
But you have many lives.
Spend a life writing poems.
Spend another building things.
Spend a life looking for facts.
Spend another looking for the Truth.
These are your lifetimes.
Use them."

I feel that the teacher in me is slowly being killed at my current position.   I'm finding it harder and harder to push the peddles on my bike each morning and feel like I can't peddle away fast enough at the end of the day.  That's never a good way to start or end your days.  I've been a teacher in Japan for nearly six years and if I finish my contract it would be a little under seven years.  Almost one life.

I'm not afraid of "death" in the sense of changing myself but I am worried about what it means for my FI journey.

I could continue this life on life support for another seven years, spend another life, and be FI as a teacher.  But I don't think that is the journey I want to take anymore.  After all it's not about killing yourself to get to FI.  I really don't want to spend my time at a job I hate becoming a bitter husk of a once formerly happy and energetic man just to limp across the finish line and be spat out a different person.

And yet I feel that staying through to the end of my contract is in a way doing the same thing.  I'll finish up in March bitter and unhappy.  Not that a change in my life at that point can't turn things around again.  But the feeling of free fall and loss of control over the next several months will drive me crazy.

Perhaps that is just part of the journey from one life to the next.

My goal is still financial independence but the path to get there is changing.

Friday, May 24, 2013

April - May Expenses


The months keep rolling on and the temperature keeps rising.  I really enjoy this time of year in Japan.  It’s right before the rainy season hits in which, next to winter, is my least favorite time.  But for a brief period it’s warm enough to bike in just shorts and a t-shirt, stay out enjoying the company of friends till all hours, and basically hit the out doors any time.  Picnics and days at the beach (as well as the end of the first term of school and summer break) are just over the hill.

Of course I still have a job which means I only really get to enjoy about 7 or 8 days max of this fine fine weather.  The other days are spent in a suit and tie in a classroom.  I don’t mind teaching, it’s a challenging, and very rewarding field.  Sure I get upset at students, and not every less plan I make is a winner.  But, it sure beats the nine to five in other fields. 

Alas teaching is still mandatory.  I must teach in order to live.  I’m aiming to one day have everything in my life be about choices.  One day I can choose to get up and go teach while the next day maybe enjoy one of those picnics or days at the beach.  In order to achieve this level of freedom I have to be careful with my money and that is why I track my expenses every month, down to my very last yen.  I do this myself in an excel workbook of my own design.  Let’s see how I did:


INCOME

Paycheck:  ¥299,484

Gympact:  ¥1,000

TOTAL:  ¥300,484

Income fell this month.  I didn’t do any work at my part time job during the March to April pay period.  I was on vacation and also preparing for the new school year that began in April.  It’s too bad that I couldn’t get any extra work in but at the same time I didn’t want to push myself beyond what I know I can handle.  In addition my job forgot to add my raise onto my paycheck (it was added to the next paycheck) and the transportation expense I thought I was going to receive is now being split up monthly so I’ll be seeing that next month.


EXPENSES

Rent:  ¥50,100

Eating Out:  ¥28,963

Groceries:  ¥15,784

Transportation:  ¥3,730

Bills:  ¥7,905

Entertainment:  ¥300

Alcohol:  ¥3,993

Bike:  ¥14,847

Travel:  ¥30,440

School Supplies:  ¥520

Fees:  ¥1,944

TOTAL:  ¥158,526

SAVINGS RATE:  47.34%

Expenses were certainly higher this month.  I paid off my credit card which included my bullet train ticket to Hiroshima in March for the bike trip I took with my GF.  It also included some bike tools like a large torque wrench, some players, and bits.  I’m happy to report there has been little to no activity on the CC lately so the coming months will be quite nice.

My savings rate for this month was 47.34% and here are the savings rates for the year.

March  42.85%

February  65.43%

January  47.36%

My average savings rate for the year is 51.88%.  This is below my target goal of 55%.  Due to the setback in receiving my raise and the extra expenses this month I once against missed my target goal.  The high savings rate for February is helping to keep my average up.  I’ve been busy at work so I haven’t been going out lately which means I see higher rates going forward for the rest of the year.  August in particular will be a good month as I get six weeks paid vacation during which time I can still work at other jobs. 
How's everybody else doing?

Friday, April 26, 2013

March – April Expenses and 1st Quarter Dividends


Things have been quite hectic lately with my school moving locations, a new route to bike, new students and lesson plans, etc.  It doesn’t mean I’ve forgotten about investing however or living a frugal life.  I can always do better at both but just giving it a shot puts me on the front lines of a happy fulfilling life where my time is my own.

I track my expenses from the 15th of one month to the 14th of the next.  Here is what happened from March to April (Numbers are in Japanese Yen):

Income:

Paycheck:  299,904

Part-time Job:  18,394

Questionnaire:  500

Selling stuff:  1,240

TOTAL:  320,038

My income was pretty much where I thought it would be.  Down quite a bit from February but that’s only because February had quite a spike in it with the STEP Eiken test and discovering 50 hours of unused vacation time from my part-time job.  Next month I will receive a raise at work (which was forgotten on my April check so I’ll get double the raise in May) and also start receiving travel expenses monthly.

Expenses:

Rent:  50,100

Eating Out:  45,364

Groceries:  10,578

Transportation:  4,950

Bills:  6,696

Entertainment:  1,200

Alcohol:  4,817

Bike:  18,666

Medical:  550

Present:  25,701

Videogames:  1,515

Lodging:  12,770

TOTAL:  182,907

SAVINGS RATE:  42.85%

AVERAGE SAVINGS RATE 2013:  51.88%

Expenses came in a bit harsh this month with some winners and a few losers.  I bought my GF a nice present for Valentine’s Day in February which means I had to pay the CC in March.  A few drinking parties with the new teachers at my school plus the spring break bug to get out and catch some brews with friends had me forking over more cash for “catheter and tube” drinks.  Bills and Medical were wayyyy down and have been down compared to last year.  I canceled my postpaid phone and went prepaid in January and I’ve been taking much better care of my teeth so my dental visits are just for checkups and maybe an x-ray. 

My yearly goal for the year is to save 55% of my income.  So far my average is 51.88%.  I’m not very worried about this going forward as I mentioned I’m receiving a raise at work and I’ll start to collect transportation expense for the train even though I am taking my bike.  In addition I don’t have any big plans for the summer so I will try to get some time in at my part time job while still collecting a paycheck from my employer (I get paid summer, winter, and spring breaks).  In addition there are still two more STEP Eiken tests this year which will help to pad my bottom line.

1st Quarter Dividends

As I buy more stocks I get paid more dividends.  It’s that simple really.  My first quarter of 2013 saw a blowout compared to last year.

Total Dividends Received 1st Quarter 2013:  $178.96

Total Dividends Received 1st Quarter 2012:  $44.17

Wow!  A more than 300% increase over last year!  I’m pretty happy with that!  Of course the best part is that all of these dividends are being reinvested so they will pay me more the next time around.  And if the company decides to increase the dividend, well, it just doesn’t get any better. 

Friday, April 12, 2013

Double Whammy

As anybody investing in stocks knows the market is pretty expensive right now.  Almost anything that I bought a year ago is up ten to twenty percent!  The market has recovered all of its value that it lost in the crash of 2008 and I'm not sure if it is showing any signs of slowing down.  Of course this makes things like the value of my portfolio look nice but in reality it's not the game that I want to be playing.  Not that it's impossible, but it is certainly more difficult to find value in this market.

Another problem that effects us expats is the exchange rate.  As any expate living abroad and sending money home is aware the exchange rate is like an extra hoop you have to bring into the equation.  For expats it's having to line up two scopes before we can pull the trigger on a deal. 

In the last two or three years living in Japan has been great!  The Japanese yen grew to new heights that had never been seen.  Of course this was not good for Japanese businesses as their products were now more expensive and exports fell.  But for us expats using yen to buy US dollars it was a breath of fresh air.  I never thought I'd ever see the day when 75 yen would buy me 1 US dollar.  Those were the days I lived in for the last three or so years.  It was like everything was 25% off including stocks, plane tickets, and gadgets.

This is not the story as of late.  Due to a change in the Japanese government, renewed consumer confidence, and an aggressive stimulus plan the yen has taveled back to being on par with the US dollar.  This means a big change for me and my salary. 

I did my best to abstain from squandering my money on frivilous items and focused on putting everything I could into stocks even during the days of a strong yen.  But I also developed an expectation of how much I could buy with my yen.  For an example let's say I was making $60,000 US dollars last year.  I did my best to save and invest and mangaged to achieve an almost %50 savings rate.  Now my salary has fallen to almost $45,000 a year.  If I continue at the same spending rate as last year my savings rate will fall to almost 33%.  Of course this isn't a complete apples to apples comparison but the point is my yen will no longer buy me the huge number of shares that it used to.

This has led me to a cross roads where I have to make a few important decisions.  Do I pick up another job and try to earn more?  Do I continue to invest in US dividend growth stocks?  Do I change my focus to the Japan domestic  market?  Where can I reduce expenses more?

Honestly I haven't made a decision yet concerning any of these.  Any other expats out there what's your take on the situation? 

Wednesday, March 27, 2013

February - March Expenses

Well here we are at almost one quarter of the year gone by!  I recently posted about a milestone I hit but that doesn't mean I'm stopping.  No surrey bob!  That is just one little step on my way to a life of choices.  In fact to be honest I should celebrate $30,000 as much as I should celebrate $30,001.  I can't make every blog post about the value of my portfolio, however, but it's still fun every now and then.

What really matters in my journey to FI are these posts right here.  My expense posts outline my spending every month.  It shows my offensive and defensive strategies and just how well they are working.  Offensive is my income.  Am I making the best use of my time or am I just slagging off on the weekends.  Defensive is my spending.  How well am I controlling my urges to buy the latest widget or gadget?  How often to I really need go out to eat with my buddies?  Let's take a look:

Income:
Paycheck:  ¥299,404
Part Time Job:  ¥102,755
Part Time Job 2:  ¥27,000
Questionnaire:  ¥5000
Total:  ¥434,159

My income was pretty insane this month.  I received my regular pay in addition I discovered some unused vacation time at my part time job and asked to receive the whole lump sum ASAP (got to get that interest working in my favor).  The Step EIKEN test was also held where I am an interviewer (part time job 2).  In addition a friend introduced me to a survey where for answering almost 400 questions in Japanese and 400 questions in English I can earn ¥5,000.  Not bad, but I have to admit it was a drag getting through it all in one sitting.  Over all this might have been my best month ever as far as income goes.

Expenses:
 Total:  ¥148,334

Expenses weren't out of line with where they usually are.  I suppose because of "Presents" it was a bit high.  This year I sent out my X-mas album late and so, I paid off my credit card in the month of February.  I track my bills by when I actually pay them so this expense landed in the second month of the year.  This should be the last month that "BIlls" will be as high as it is.  I'm completely clear of my old cellphone bill now, and riding high on prepaid.

My target savings rate for the year is 55%.  So far I've hit:

January - February:  47.36%
February - March:  65.43%

My average savings rate for the year is 56.40%.  Not bad!  It looks like we are back on track.  I'll admit that March - April is already shaping up to be a bit of a struggle with end of year school parties, a bike trip, and possibly a fun weekend at Fujikyu Highlands.  I'm all about enjoying my money while I have it as well, but I am sure not gong to forget about my goals. 

Thursday, March 7, 2013

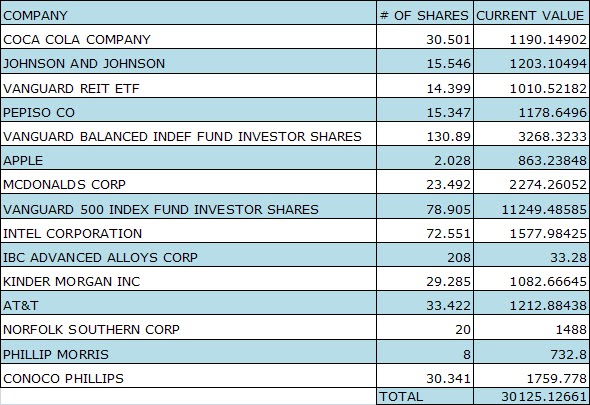
Milestone: Portfolio Surpasses $30,000!

I've been in Japan for the last little while but that doesn't mean I haven't been watching the market.  If you haven't been following, the market is on fire like the flames from Mt. Doom (in Mordor).  Because of that it's pushed my portfolio passed the $30,000 mark!  This is a big achievement for me.  I have never had this much money at my finger tips before.

I could, if I so wanted, go out and buy a Mini Cooper right now with zero need to go to a bank.  I could, if I was so persuaded, take a huge long vacation staying in expensive hotels and dining at the finest restaurants.  I could even, if the feeling so arose, pay for a six year college education including one year of study abroad in Japan (I should know).

However I don't feel like doing any of those things.  In fact the next vehicle purchase I make will probably be more than ten years down the road and it will be a bike.  My next vacation is being taken on a bike.  And, although I don't think I'm going back to school anytime soon (not that I didn't have a good time), my next educational foray will probably be via Treehouse.

Perhaps the surreal thing is that although it took me about four years to pay off six years of college, credit cards, and a car, it's only taken me fourteen months to save up a stash equating to 85% of that same amount.  That really demonstrates: how interest rates kill you if you aren't on the receiving end of them, and the job of money is to make money.

Back in January I revealed for the first time what I am holding.  At that time my portfolio was worth $25188.70.  With the recent drive in value by the market I just hit $30125.13!  That's an increase of almost $5000 in about two months.  Not to keeping adding cherries on top but I still have capital that I want to deploy.


I'm not a genius.  Looking at my portfolio people might be confused.  "Apple!?  That's not a dividend paying stock!"  "Why's he buying individual equities but also Vanguard 500?"  Well that's because I'm not a genius.  And yet here I am on my way to FI.  I am also not a big enough fool to think this can't go back down.  In addition it's more about how much the portfolio firing off in dividends than it's actual total value.  But I'm not going to ignore the obvious correlation between portfolio size and dividend payout.  Put simply "the more, the more."

Frankly a stock sell off would be pretty cool right now as it's getting harder to find good values.  But in the mean time I'll enjoy the view from 30,000.

Mata ne,

Kechi